Finance

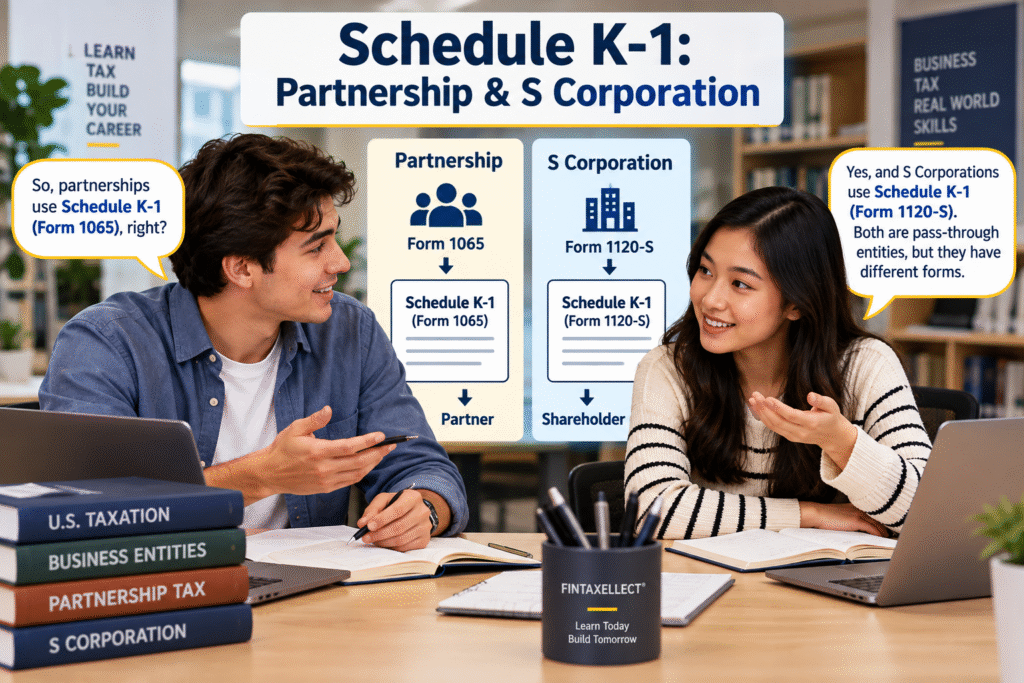
Schedule K-1: Partnership & S Corporation

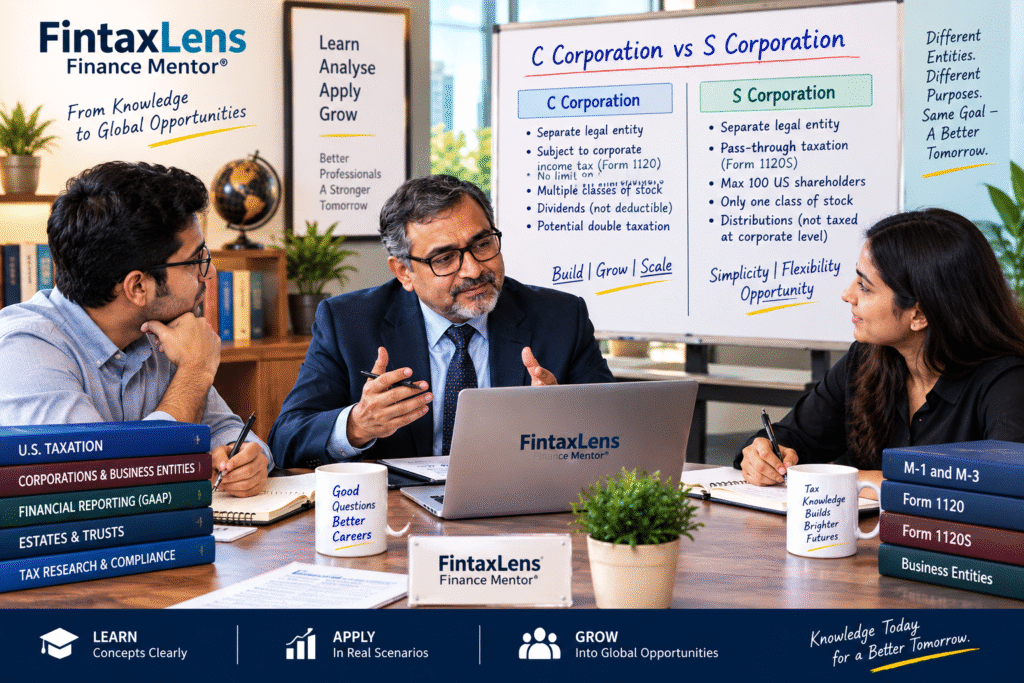
After understanding the basic differences between a C Corporation and an S Corporation, the next important concept in U.S. business taxation is Schedule K-1. For students, accountants, and professionals preparing for careers in U.S. tax, accounting, audit, or consulting, K-1 is an essential concept because it connects a pass-through entity with its owner’s tax reporting.

Schedule K-1: Partnership & S Corporation Read More »

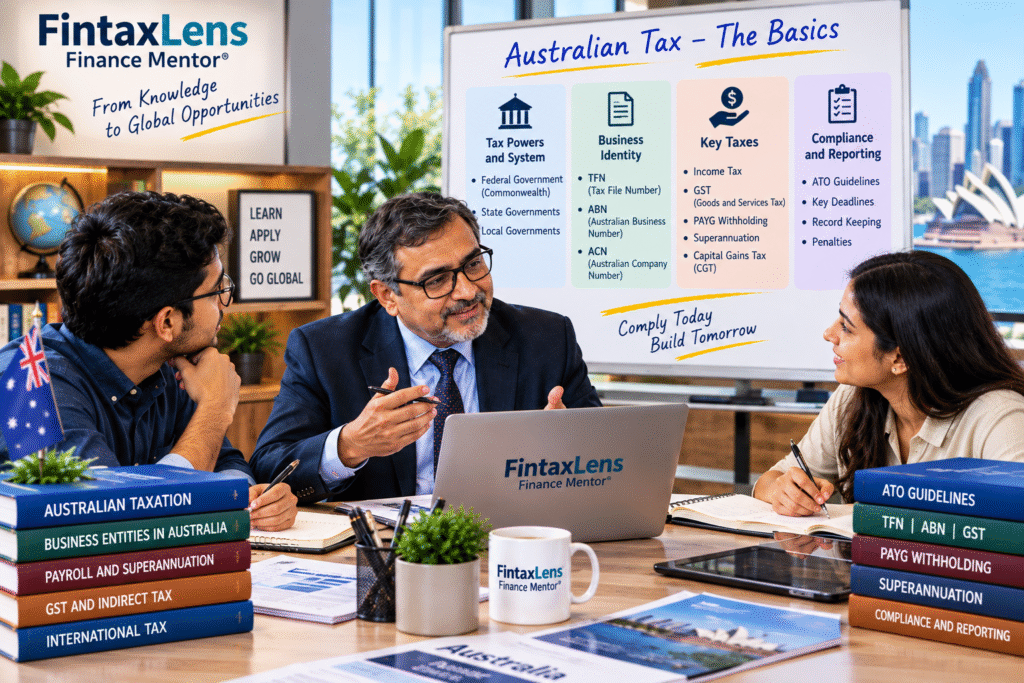
Tax Powers & Business Identities in Australian Taxation

STUDENT: Professor, whenever I hear the words Australian Taxation, I feel there are too many terms to remember. Where should I start? PROFESSOR: Don’t start by memorising terms. Start by asking a simple question: Why does a government need taxes? STUDENT: To collect revenue? PROFESSOR Exactly. Governments need revenue to provide public services such as

Tax Powers & Business Identities in Australian Taxation Read More »

Trusts vs. Non-Profits – Decoding Form 1041 and Form 990 (With Case Study)

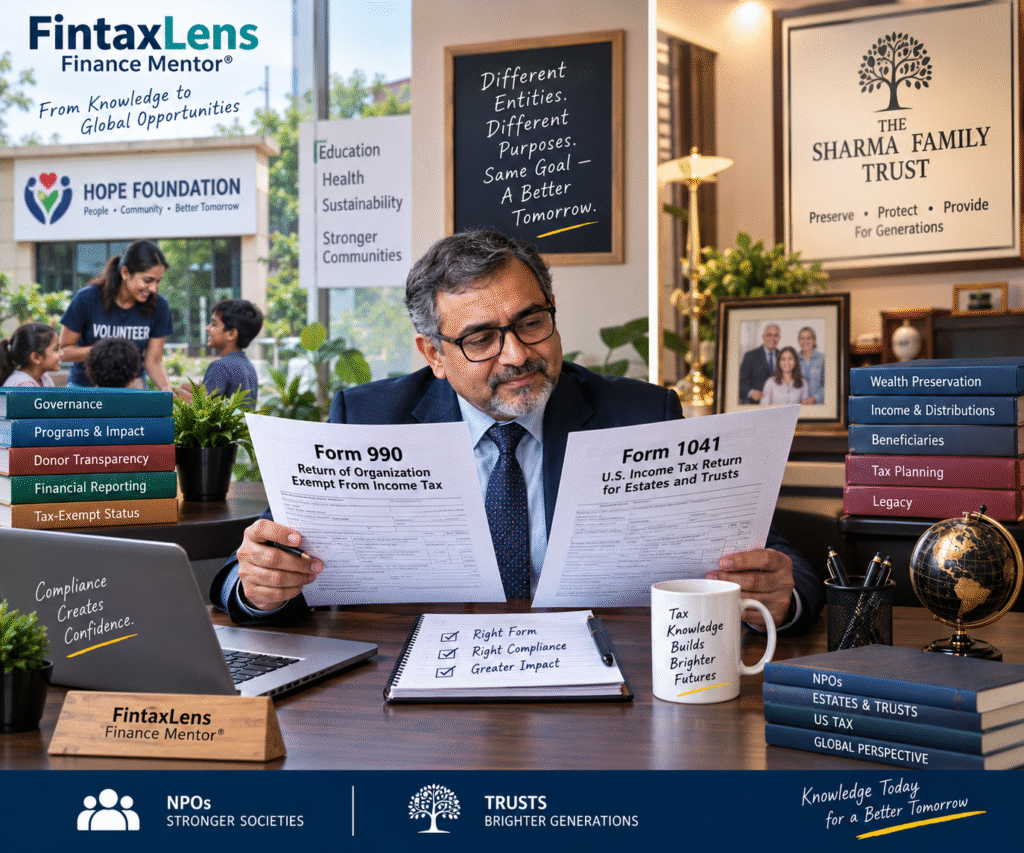
When we think about U.S. federal income tax returns, Form 1040 usually comes to mind. But what happens when the taxpayer is not an individual? A nonprofit organization, a deceased person’s estate, or a trust may have completely different federal filing obligations. Two important forms in this area are: Form 990 — Return of Organization

Trusts vs. Non-Profits – Decoding Form 1041 and Form 990 (With Case Study) Read More »

Cost of Goods Sold (COGS)

UNDERSTANDING Cost of Goods Sold (COGS) in the Manufacturing Industry

1.  Backdrop       Good morning, everyone.      Professor:  Today I don’t want you to write any formula , just a simple story about school bags. Student 1:  Sir, no formula? That’s unusual for Costing! Professor:  Exactly! Today, I want you to think like a business owner. Suppose you manufacture 1,000 school bags. You spend ₹2,00,000

UNDERSTANDING Cost of Goods Sold (COGS) in the Manufacturing Industry Read More »

Fixed Assets

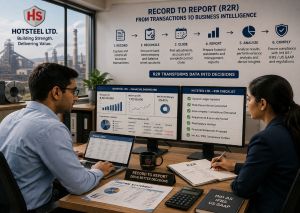
RECORD-TO-REPORT (R2R)

Transforming Financial Data into Business Intelligence Many finance professionals assume that accounting ends when journal entries are posted and financial statements are prepared. However, in modern organizations, accounting is no longer a mere record-keeping function. It has evolved into a strategic business process that supports managerial decision-making, operational control, regulatory compliance, and business growth. Record-to-Report

RECORD-TO-REPORT (R2R) Read More »

Don`t copy text!