
Minimum Alternate Tax (MAT): Concept and Practical Application
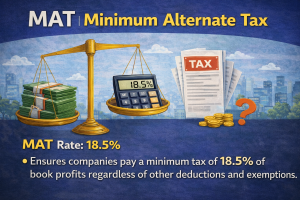
Minimum Alternate Tax (MAT) is an important provision under the Income Tax Act, 1961, designed to ensure that taxpayers with substantial income do not avoid tax liability by claiming various deductions and exemptions. However, students often face confusion regarding its applicability, computation, and differences. To build conceptual clarity, case-based learning can be highly effective. By
Minimum Alternate Tax (MAT): Concept and Practical Application Read More »