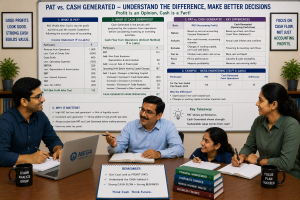
PAT vs Cash Flow from Operating Activities: A Practical Understanding under AS 3
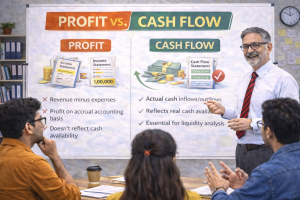
In the world of accounting, “profit” and “cash” are not always the same. A company may report a strong Profit After Tax (PAT) under the Statement of Profit & Loss prepared in accordance with GAAP, Accounting Standards and Schedule III of the Companies Act, yet still face cash shortages in day-to-day operations. This happens because
PAT vs Cash Flow from Operating Activities: A Practical Understanding under AS 3 Read More »