| The Rules Every Taxpayer Should Know |
PART 1 · U.S. INTERNATIONAL TAXATION SERIES
Moving to or from the United States can change the tax treatment of an entire year.
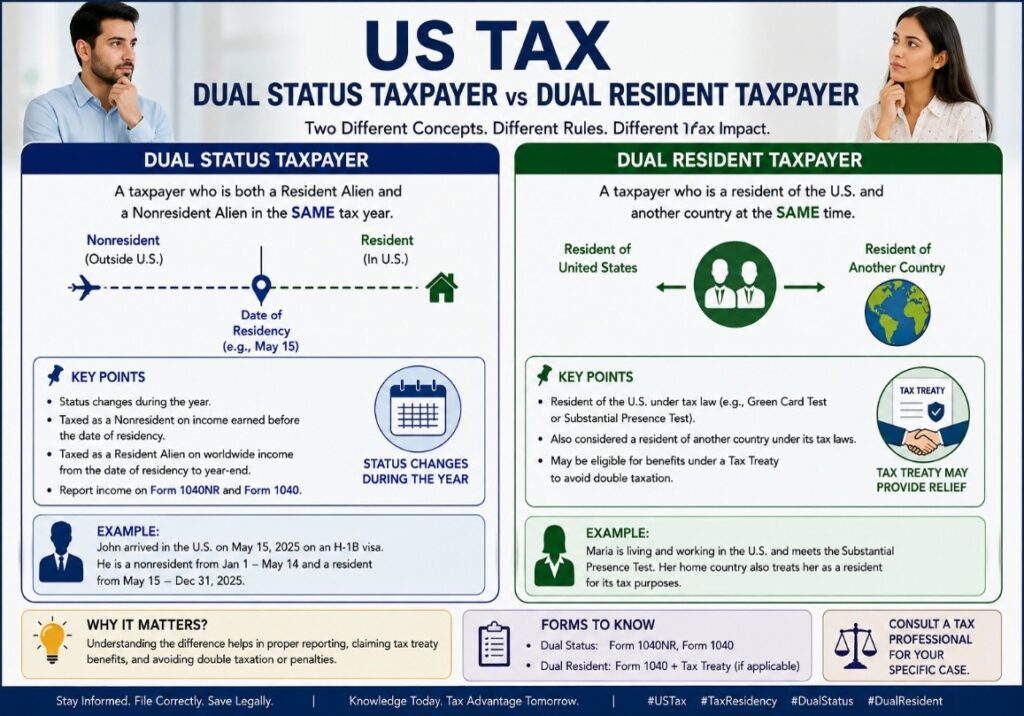
A person who moves between India and the United States during a tax year may face a unique U.S. tax situation. For part of the year, the individual may be a nonresident alien, while for another part, the individual may be a resident alien. This is known as a dual-status tax year.
But don’t confuse this with being a dual-resident taxpayer. Although the terms sound similar, they describe two different situations. Let’s understand the basic rules.
1. What is a Dual-Status Taxpayer?
A dual-status taxpayer is an individual who is both a U.S. resident and a nonresident during the same tax year. This commonly occurs in the year a person enters or leaves the United States.
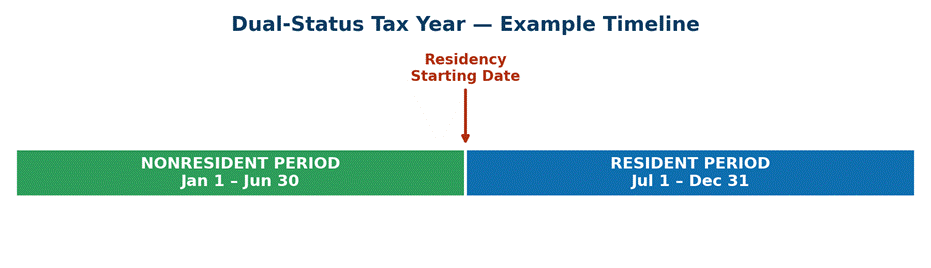
Example: residency begins on July 1, splitting the year into two periods.
| DUAL STATUS IS ABOUT A CHANGE IN U.S. TAX STATUS DURING THE YEAR |
2. What is a Dual-Resident Taxpayer?
A dual-resident taxpayer is different. Here, the individual is treated as a resident under the domestic tax laws of two countries — for example, resident in the United States and resident in India at the same time. In such a situation, the applicable tax treaty may need to be examined to determine the taxpayer’s treaty residence.
Easy Memory Rule
| Dual status = two U.S. tax statuses in one year. Dual resident = residence claimed by two countries. |
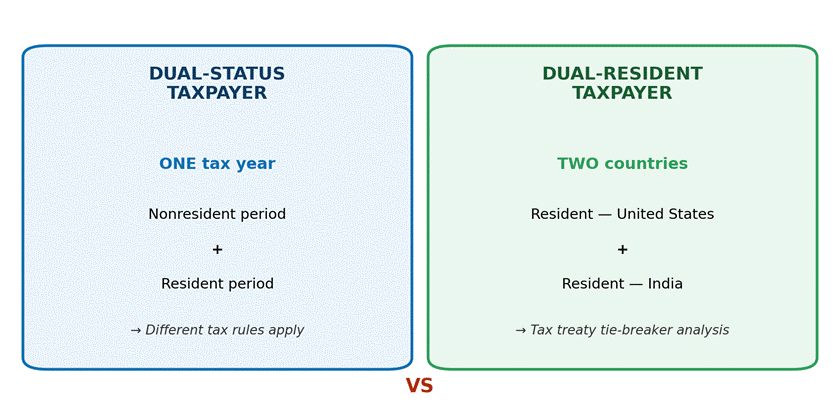
Dual-Status vs. Dual-Resident — at a glance.
3. How Does a Person Become a U.S. Tax Resident?
For a non-U.S. citizen, two major domestic-law tests determine U.S. tax residency. A person satisfying either test is generally treated as a U.S. resident for federal income tax purposes, subject to applicable exceptions and special rules.
▶ Green Card Test
▶ Substantial Presence Test (SPT)
4. Green Card Test
An individual generally satisfies the Green Card Test if the person is a lawful permanent resident of the United States at any time during the calendar year. A lawful permanent resident generally holds a Permanent Resident Card, commonly known as a Green Card.
| U.S. tax residency does not require U.S. citizenship. A non-U.S. citizen can become a U.S. tax resident through the Green Card Test. |
5. Substantial Presence Test — SPT
The Substantial Presence Test is primarily a day-counting test. Generally, an individual must be physically present in the United States for at least 31 days during the current year, and have at least 183 weighted days over the current year and the two preceding years.
The Calculation
| Component | Weight |
| Current-year days | 100% |
| Preceding-year days | 1/3 |
| Second-preceding-year days | 1/6 |
Worked Example
Suppose an individual has 120 days in the U.S. in 2026, 120 days in 2025, and 60 days in 2024.
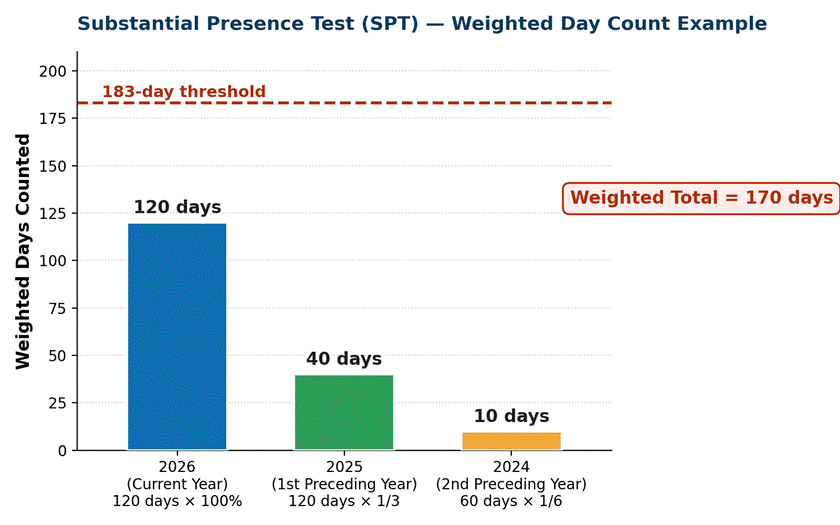
Weighted total = 170 days — below the 183-day threshold.
Since the weighted total is below 183, the individual does not satisfy the 183-day requirement based on these figures alone. The IRS provides specific rules concerning days that may be excluded or treated differently, so the SPT should not be calculated merely by counting travel days.
6. Residency Starting Date — The Critical Point
Suppose a foreign individual becomes a U.S. resident during the year. The next question is: from what date does U.S. residency begin? This is the residency starting date. It is extremely important because it divides the tax year into a nonresident period and a resident period. The IRS has specific rules for determining the residency starting date depending on how residency is established.
7. Why Does the Residency Date Matter?
| Period | U.S. Tax Treatment |
| Nonresident Period | U.S.-source income + income effectively connected with a U.S. trade or business |
| Resident Period | Worldwide income |
The IRS explains this fundamental difference between nonresident and resident taxation.
8. A Simple India–U.S. Illustration
Suppose Ravi, an Indian citizen, moves to the United States on July 1 and becomes a U.S. tax resident from that date. Before moving, Ravi earns salary in India. After moving, he earns U.S. salary, Indian bank interest, Indian rental income, and U.S. bank interest.
The analysis cannot simply begin by adding all the income together. First determine:
▶ Step 1 — When did U.S. residency begin?
▶ Step 2 — Which income belongs to the nonresident period?
▶ Step 3 — Which income belongs to the resident period?
During the resident period, Ravi’s worldwide income generally becomes relevant for U.S. tax purposes. This is why the residency starting date is one of the most important concepts in international taxation.
9. What If India Also Treats Ravi as a Resident?
Now the analysis becomes more interesting. Suppose Ravi is resident under U.S. domestic law and resident under Indian domestic law. He may be a dual-resident taxpayer. The next stage is to examine the applicable India–U.S. tax treaty and determine whether treaty residence and tie-breaker provisions affect the result. This is different from simply being a dual-status taxpayer.
Memory Tool
| Dual-Status | Dual-Resident |
| One tax year | Two countries |
| Nonresident period → Resident period | Two domestic-law residence claims |
| Different tax rules | Treaty analysis |
The Golden Rule
| STATUS → DATE → SOURCE → INCOME |
First determine the taxpayer’s status. Then determine the residency starting or ending date. Then identify the source of income. Finally, determine the income taxable in each period.
What Comes Next?
Knowing the rules is only the beginning. In Part 2 — Elections, Forms & Filing Formalities — we will examine:
▶ Closer Connection Exception — Form 8840
▶ First-Year Choice
▶ Nonresident-spouse election
▶ Form 1040
▶ Form 1040-NR
▶ Dual-Status Return
▶ Dual-Status Statement
▶ Form 8833
▶ and the practical filing formalities
Then, in Part 3, we will apply everything ete India-to-USA case study.
Very Insightful blog, thank you sir.