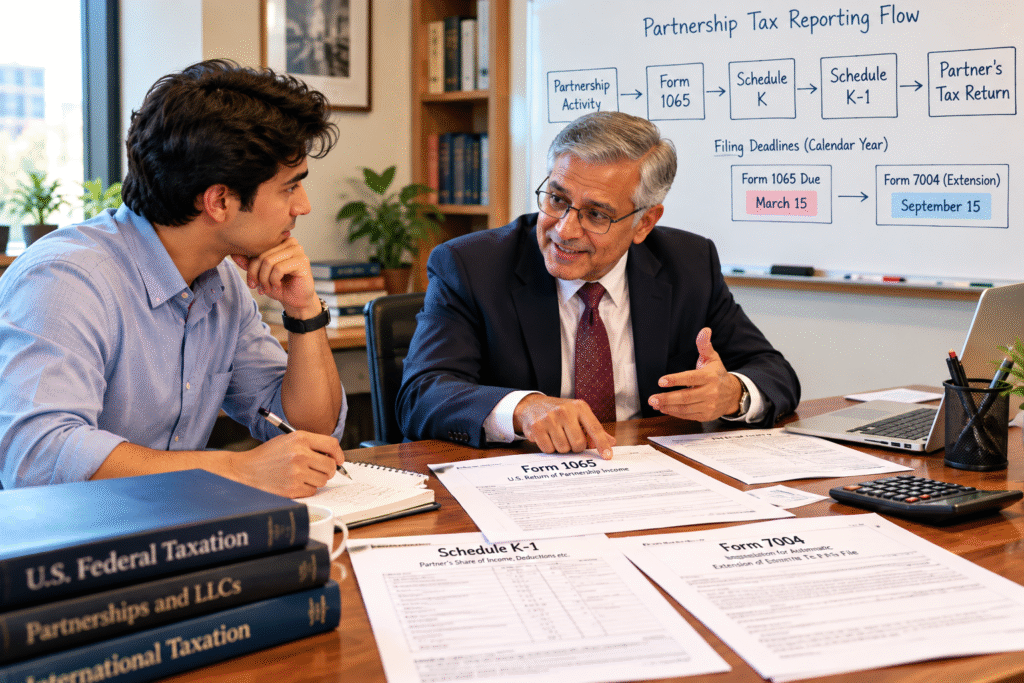
Andrew came into the Professor’s office with his notebook. He had understood the basics of partnerships, but now he wanted to understand the Form 1065 Tax Return and how a partnership reports its income to the IRS.
He opened it to the page where he had written:
Andrew: Professor, I think I finally understand the basic structure of partnership taxation.
Professor: Good. Then you are ready for the next question.
Andrew: Form 1065?
Professor: Exactly.
Andrew: I know Form 1065 is the partnership tax return. But I still have several questions.
Professor: Then let’s begin.
What is Form 1065?
Andrew: Professor, what exactly is Form 1065?
Professor: Form 1065 is the U.S. Return of Partnership Income. It is the principal federal tax return used by a partnership to report its income, deductions, gains, losses and other required information.
Andrew: But didn’t we say that a partnership generally doesn’t pay federal income tax at the entity level like a C corporation?
Professor: Correct.
Andrew: Then why does it need to file a tax return?
Professor: Because not paying federal income tax at the entity level does not mean that the partnership has no federal tax reporting responsibility.
The partnership still reports relevant tax information so that the IRS and the partners can determine how partnership tax items are treated.
ANDREW’S NOTEBOOK
NO ENTITY-LEVEL FEDERAL INCOME TAX ≠ NO TAX RETURN
Who is Required to File Form 1065?
Andrew: So, does every partnership file Form 1065?
Professor: Generally, a domestic partnership must file Form 1065 for its tax year, subject to applicable exceptions and special rules.
Andrew: Even though the income generally flows through to the partners?
Professor: Yes. Flow-through taxation does not eliminate partnership-level reporting.
REMEMBER THIS
Flow-through taxation ≠ no reporting
The partnership reports its relevant tax information, while partners generally take their respective tax items into account on their own returns.
What Does Form 1065 Report?
Andrew: What information actually goes into Form 1065?
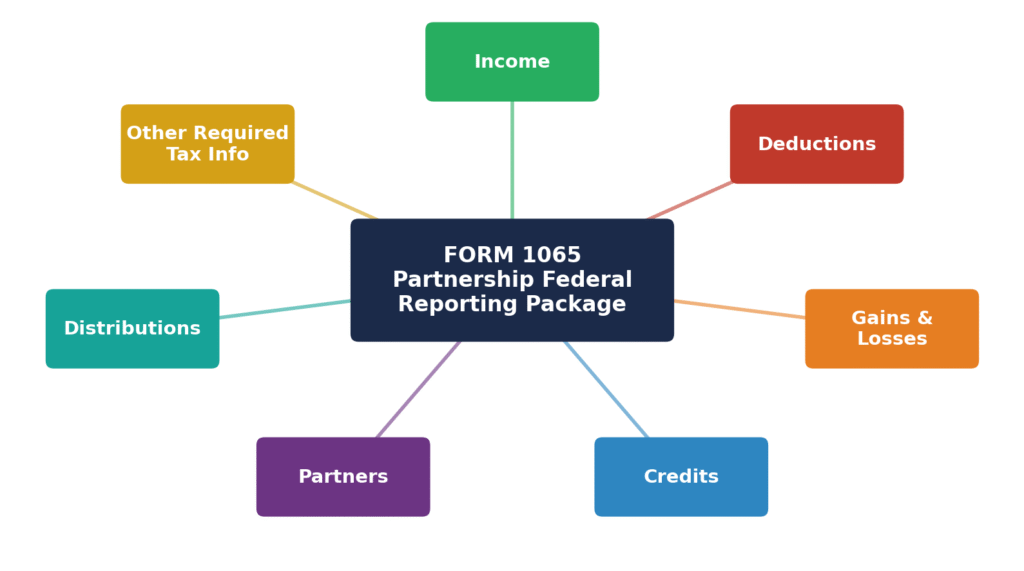
Professor: Think of Form 1065 as the partnership’s federal tax reporting package.
It generally reports information relating to:
- Income
- Deductions
- Gains and losses
- Credits
- Partners
- Distributions
- Other required tax information
Andrew: So, it is not simply a statement saying, “Our partnership earned $X”?
Professor: Exactly. Partnership taxation involves various tax items that may need to be separately identified and communicated to the partners.
Andrew: And that’s where Schedule K comes in?
Professor: Very good.
Form 1065 and Schedule K
Andrew: What is Schedule K?
Professor: Schedule K summarizes certain partnership-level tax items relevant to the partners collectively. Think of it as part of the bridge between the partnership’s tax return and partner-level reporting
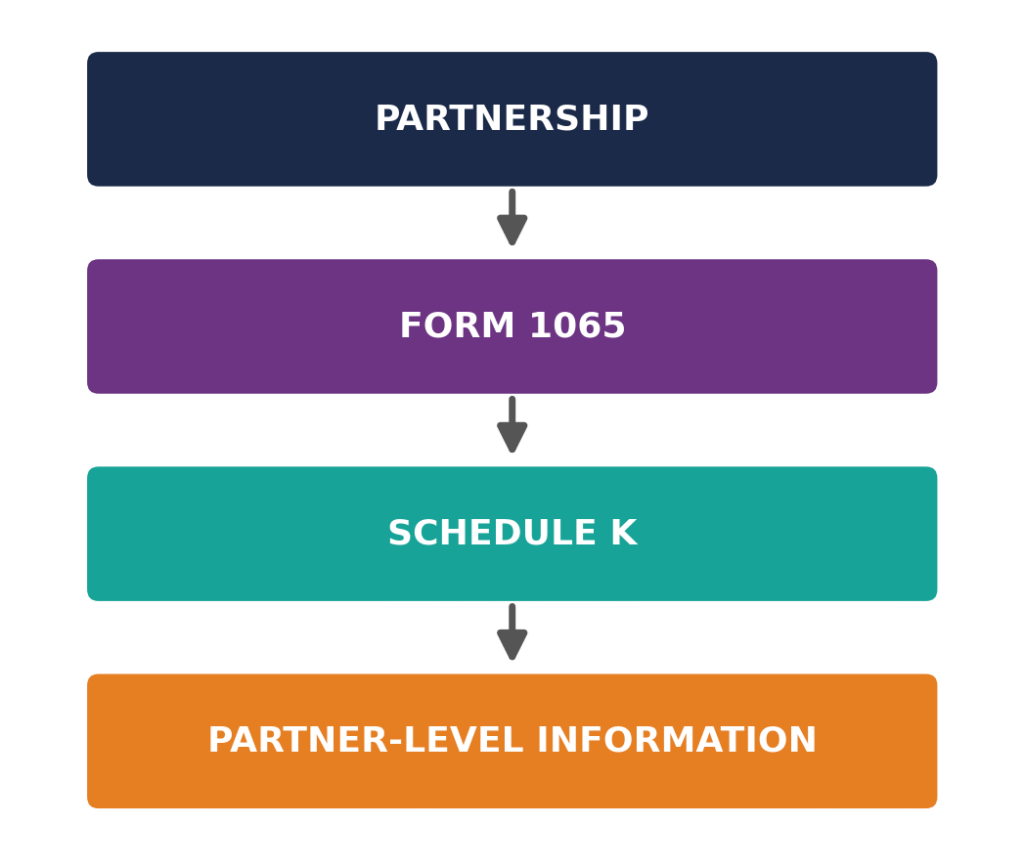
Andrew: So, Schedule K gives us a partnership-level summary?
Professor: Correct. But now comes another important form.
Then What is Schedule K-1?
Andrew: What’s the difference between Schedule K and Schedule K-1?
Professor: Schedule K summarizes certain partnership items for the partnership as a whole.
Schedule K-1, on the other hand, reports the relevant share of partnership items attributable to a particular partner.
Andrew: So, each partner receives their own K-1 information?
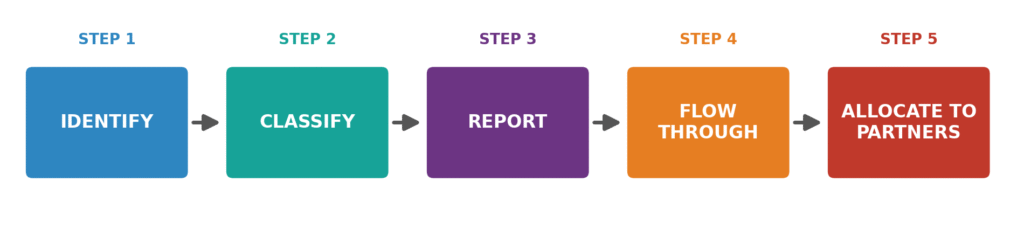
Professor: Exactly. Think of it this way:
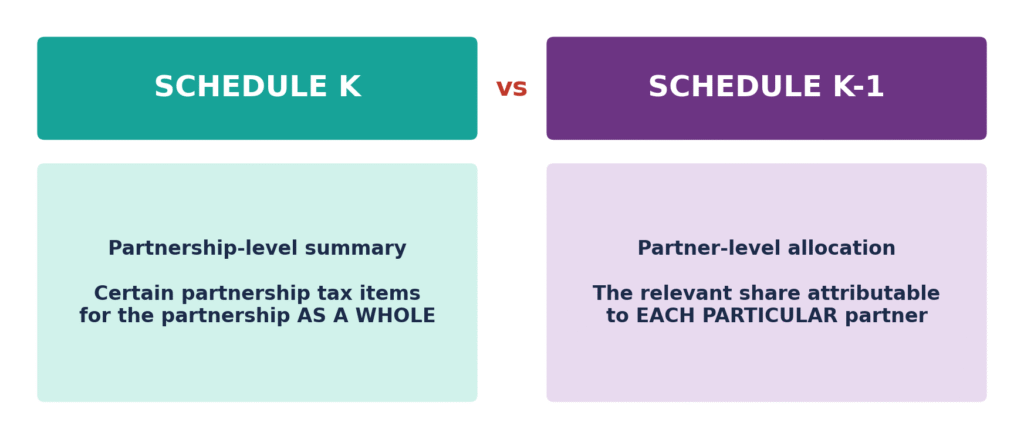
Andrew: So, K-1 connects the partnership return to the partner’s own tax reporting.
Professor: Precisely.
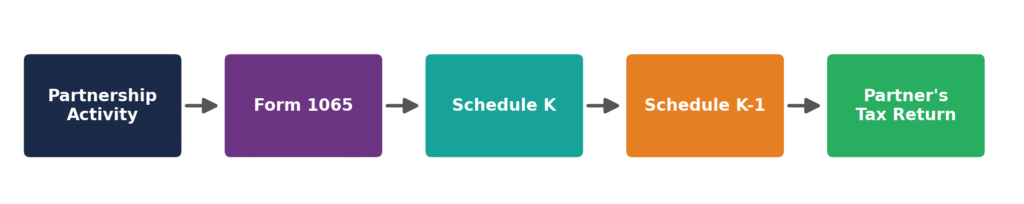
Andrew Tries an Example
Andrew: Professor, can we take a simple example?
Professor: Certainly. Suppose ABC Partnership has three partners:
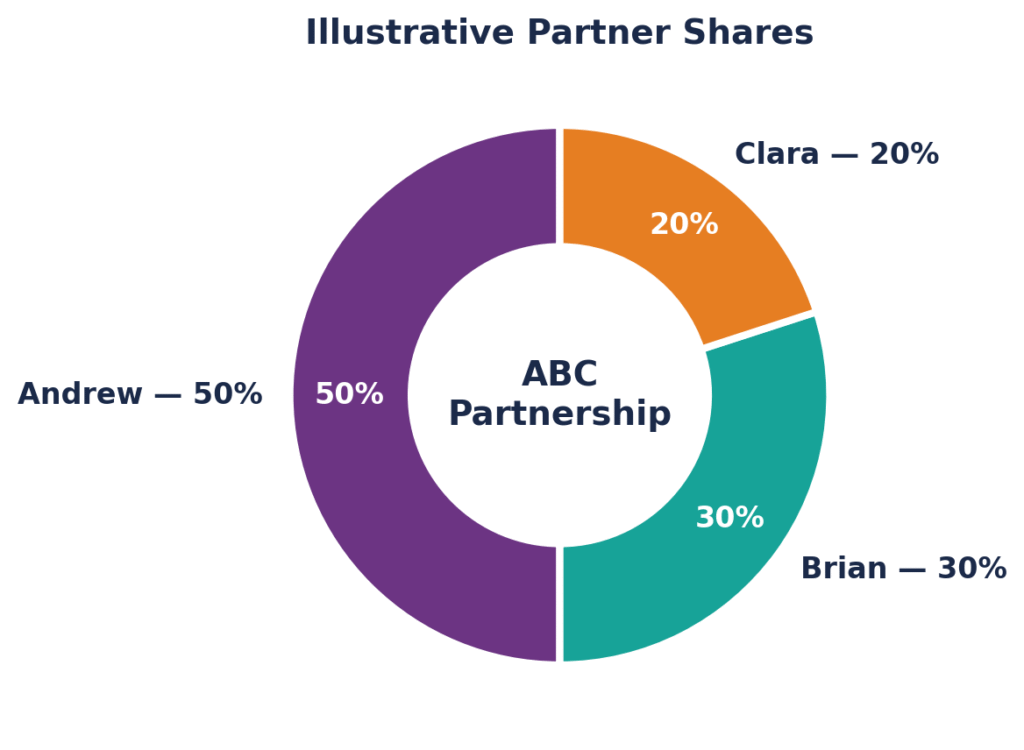
Assume, purely for illustration, that the partnership has an item of income allocated among the partners according to the applicable allocation rules.
Andrew: The partnership reports the item on Form 1065?
Professor: Yes.
Andrew: And the relevant partnership-level amount is reflected in the appropriate schedules?
Professor: Correct.
Andrew: Then my K-1 tells me my relevant share?
Professor: Exactly.
Andrew: So, my K-1 isn’t the partnership’s entire tax return.
Professor: Correct. It communicates the relevant tax information attributable to you as a partner.
| When is Form 1065 Due? |
Andrew: Professor, when does Form 1065 have to be filed?
Professor: Generally, a domestic partnership must file Form 1065 by the 15th day of the third month following the close of its tax year.
For a calendar-year partnership, that generally means March 15.
EXAMPLE
Tax year ends: December 31, 2025
General due date: March 15, 2026
If the due date falls on a Saturday, Sunday or applicable legal holiday, the deadline moves to the next qualifying business day.
Andrew: So, can partnership returns have an earlier deadline than many individual returns?
Professor: Correct. That’s why partnership tax professionals must keep the filing calendar clearly in mind.
What If the Partnership Needs More Time?
Andrew: Suppose the partnership cannot complete Form 1065 by the due date. What happens?
Professor: The partnership can generally request an automatic extension of time to file by using Form 7004 — Application for Automatic Extension of Time To File Certain Business Income Tax, Information, and Other Returns.
Andrew: So, Form 7004 is not the partnership tax return?
Professor: Correct.
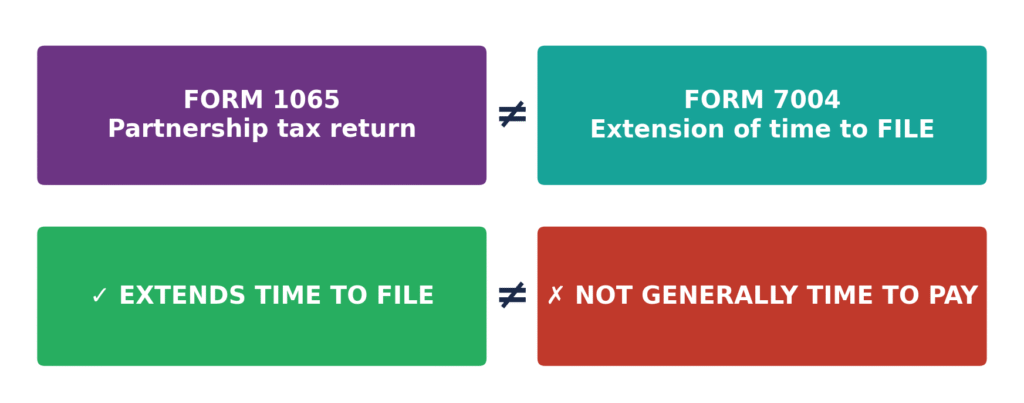
DON’T MIX THEM UP
FORM 1065 → Partnership tax return
FORM 7004 → Extension of time to file
When is Form 7004 Filed?
Andrew: When should Form 7004 be filed?
Professor: Generally, it must be filed on or before the due date of the applicable return.
For a calendar-year partnership:
- Form 1065 due date → March 15
- Form 7004 → Generally filed by the original due date
A timely Form 7004 generally provides a six-month extension of time to file Form 1065, subject to applicable rules
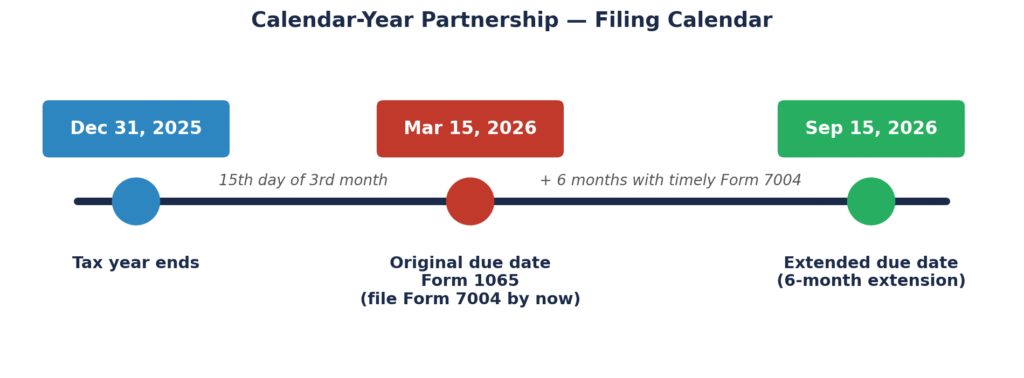
Andrew: So, the filing deadline generally moves from March 15 to September 15?
Professor: Correct, for a calendar-year partnership obtaining the applicable six-month extension.
One Very Important Point
Andrew: Professor, does Form 7004 give the partnership more time to pay?
Professor: Be careful, Andrew.
CAUTION
FORM 7004 EXTENDS THE TIME TO FILE.
It does not generally extend the time to pay tax.
Andrew: So, an extension to file and an extension to pay are different concepts?
Professor: Exactly
Andrew wrote:
EXTENSION TO FILE ≠ EXTENSION TO PAY
Andrew Connects Everything
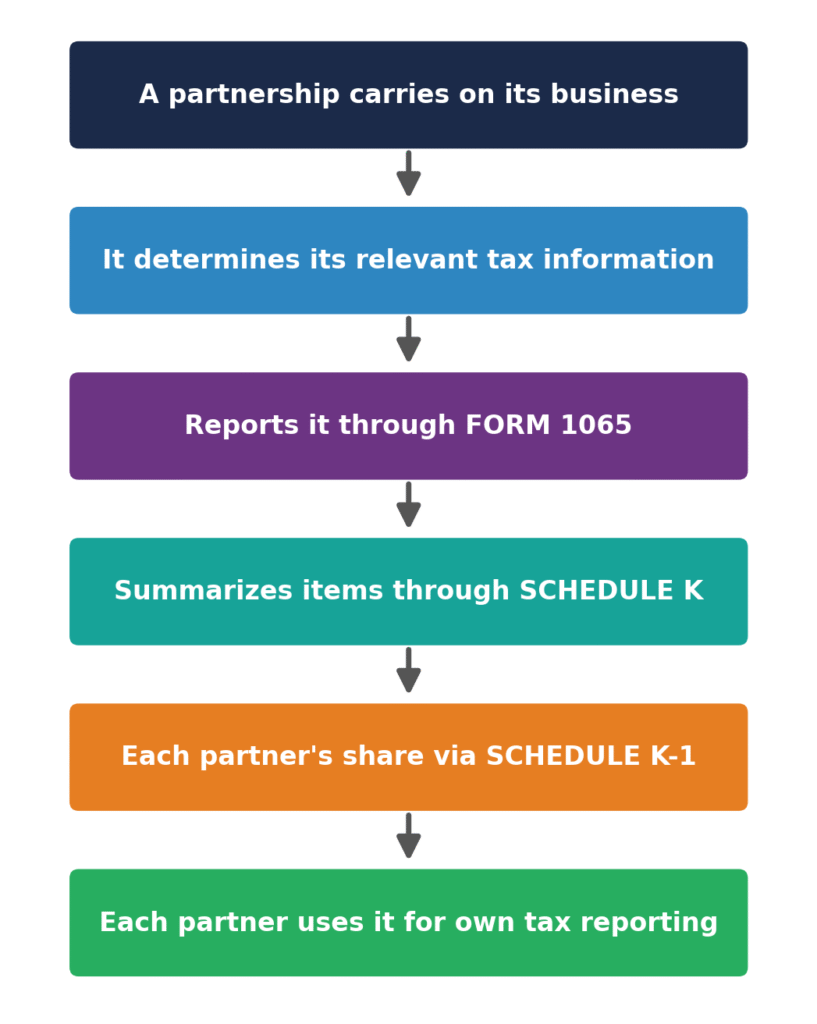
Andrew: Let me see if I have understood the complete process.
AND IF THE PARTNERSHIP NEEDS MORE TIME
Form 7004 → Extension of time to file
Professor: Excellent.
Andrew: Now Form 1065 doesn’t look like an isolated form anymore.
Professor: That’s the whole point
⭐ KEY TAKEAWAY
FORM 1065 REPORTS.
SCHEDULE K SUMMARIZES.
SCHEDULE K-1 ALLOCATES
And remember: FORM 7004 EXTENDS THE TIME TO FILE — NOT GENERALLY THE TIME TO PAY.
Professor’s Final Message to Andrew
Andrew: Professor, I understand now why you keep telling me not to memorise forms individually.
Professor: Exactly. Understand the relationship between them. Write this down:
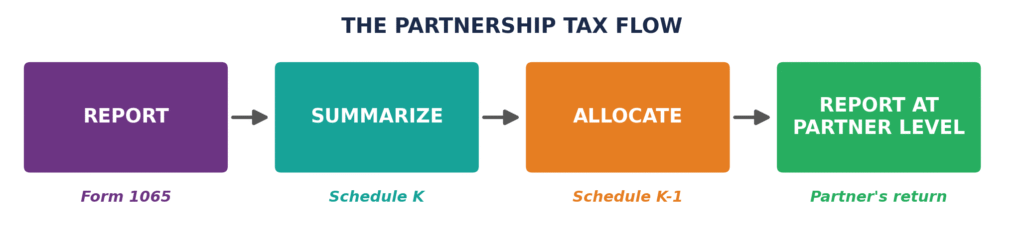
And when more filing time is required: FORM 7004 → EXTEND TIME TO FILE
Andrew: So, the forms really telling a story.
Professor: Precisely.
THE STORY OF THE FORMS
Form 1065 tells the partnership’s tax story.
Schedule K summarizes the relevant partnership tax items.
Schedule K-1 tells each partner their relevant share.
DISCLAIMER
For educational purposes only. This content provides a high-level overview of U.S. federal tax fundamentals for students and should not be construed as tax, legal, or professional advice. U.S. federal tax rules can vary depending on the taxpayer’s facts, entity classification, tax year and applicable exceptions. Always refer to current IRS instructions and applicable law before filing.
Understood very well sir.